Last Updated September 22, 2026
Standard homeowners insurance was never built with beehives in mind, and the coverage gap this creates catches a lot of beekeepers off guard. In most cases, the hive boxes and frames themselves are covered as personal property or “other structures,” the same category a shed or fence falls into — but the bees living inside them are frequently excluded, and liability for a sting-related injury only kicks in if you can be shown to have been negligent, which is a genuinely high bar to clear. The moment beekeeping becomes even a small side business, homeowners coverage typically stops applying almost entirely, and a single claim can also put your policy at risk of non-renewal down the road. None of this is meant to discourage anyone from keeping bees — it’s simply a coverage gap worth understanding clearly up front, the same way a new dog owner should understand their policy’s breed exclusions before bringing a puppy home.
This guide covers what a standard homeowners policy actually covers and excludes for backyard beekeeping, why insurers treat bees the way they treat high-risk dog breeds, the specific risks of keeping hives on someone else’s property, when you need dedicated beekeeping or farm liability insurance instead, and the practical steps to take before your first colony arrives.
Key Takeaways
- Hive equipment is typically covered under personal property or “other structures” coverage, but the bees themselves are often specifically excluded.
- Liability coverage for a sting injury generally requires proof of negligence — simply owning bees isn’t automatically covered or automatically excluded.
- Insurers can choose not to renew a policy after a bee-related claim, even if that claim was paid, because it establishes a known, ongoing risk.
- Selling honey or other hive products, even casually at a farmers market, typically moves you outside standard homeowners coverage into business/product liability territory.
- Keeping hives on rented or borrowed land requires its own liability agreement — the property owner’s insurance doesn’t automatically cover your bees.
Table of Contents
- What Homeowners Insurance Covers: Equipment vs. Bees
- Liability Coverage and the Negligence Standard
- The Non-Renewal Risk After a Claim
- Should You File a Claim? Running the Premium Math
- Why Insurers Treat Bees Like High-Risk Dog Breeds
- When Beekeeping Crosses Into Business Insurance Territory
- Keeping Hives on Someone Else’s Property
- Dedicated Beekeeping and Farm Liability Insurance
- Practical Steps Before Your First Hive Arrives
- When Wild Bees Damage Your House: Removal vs. Resulting Damage
- Protecting a Future Claim, Starting Today
- Frequently Asked Questions
What Homeowners Insurance Covers: Equipment vs. Bees
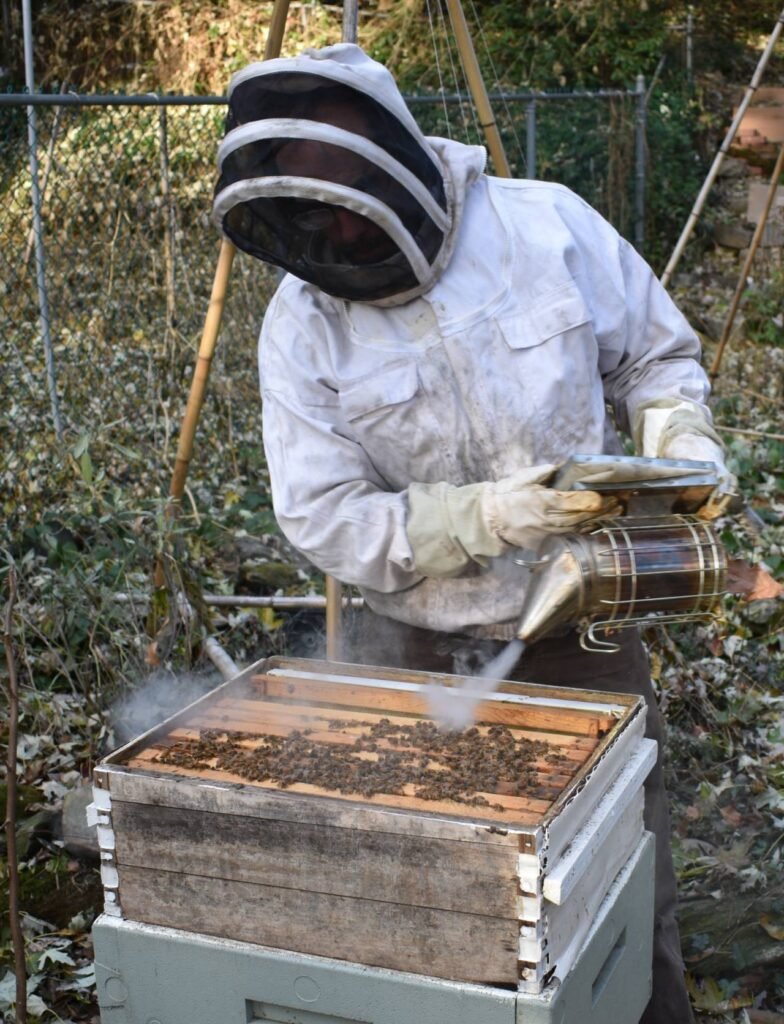
Most standard homeowners policies split coverage into a few distinct buckets, and beekeeping equipment tends to land in a more favorable one than the bees themselves. According to NYCM Insurance, hive boxes, frames, and related equipment are generally treated as personal property. Depending on the policy, a permanently-placed hive structure can also fall under a standard policy’s “Coverage B – Other Structures” section, the same category that protects a detached shed, fence, or garage against fire, windstorm, or vandalism — though exact category naming and what counts as a qualifying structure varies by insurer, so confirm the specific language in your own policy. The bees living inside those boxes are a different story: they’re frequently excluded from coverage outright, which means a colony lost to theft, vandalism, or a covered peril like fire may not be reimbursed the way the empty equipment would be. This split matters more than it might first appear, since the bees themselves — not the wooden boxes — represent the real financial investment in an established colony, particularly once you factor in a proven queen and a season or two of built-up comb.
Liability Coverage and the Negligence Standard
The more important question for most beekeepers isn’t property coverage — it’s liability. If a neighbor or guest is stung on your property, your homeowners liability coverage could apply, but generally only if you were negligent in some identifiable way, such as knowing about an aggressive hive and failing to address it, or placing hives in clear violation of a local setback ordinance. A stray sting that happens despite reasonable, compliant hive management is a much harder case for a claimant to win, and insurers know this. That said, “generally covered if not negligent” is not the same as “guaranteed covered,” and the exact language varies by insurer and by state. Reading your policy’s actual exclusions section, rather than relying on a verbal assurance from an agent, is the only reliable way to know where your specific policy draws that line.
The Non-Renewal Risk After a Claim
A detail many beekeepers don’t learn until it happens to them: even when an insurer pays out a bee-related claim, that claim creates a documented, known risk on your file. Insurance exists to cover losses that are sudden and accidental, not risks the insurer now knows are ongoing, and some companies respond to a paid bee-related claim by declining to renew the policy at the next cycle rather than raising the premium. This is worth weighing before filing a small claim for a minor loss — sometimes absorbing a small cost directly is the better move for keeping your policy intact long-term. This is the same calculation many homeowners already make with minor water-damage or storm claims, where filing on a small loss can cost more in future premium increases than it recovers.
Should You File a Claim? Running the Premium Math
Non-renewal is the worst case; the more common cost of a small claim is a higher premium. A single homeowners claim commonly raises annual premiums by roughly 9% to 20%, and that increase typically stays on your rating history for three to five years. On a moderate loss — say a $1,500 repair after a $1,000 deductible leaves $500 actually paid out — the cumulative premium increase over those years can easily exceed what the insurer paid you. Before filing on anything small, run the numbers on your own policy: repair cost minus deductible, versus your estimated premium increase over three to five years.
Why Insurers Treat Bees Like High-Risk Dog Breeds
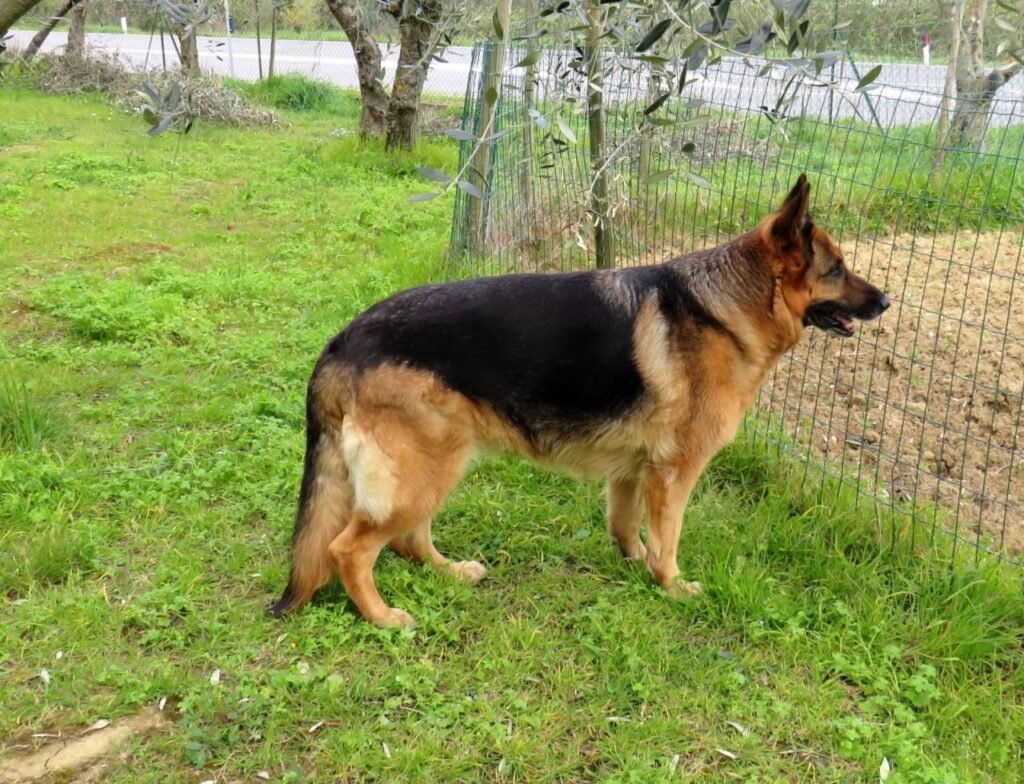
The underwriting logic behind bee exclusions closely mirrors how homeowners insurers treat certain dog breeds. Insurers commonly restrict coverage for breeds like Rottweilers, pit bulls, and German shepherds based on claims-payout history and bite-injury statistics, and dog-bite liability cost homeowners insurers hundreds of millions of dollars in settlements in a single recent year alone. Bees get a milder but structurally similar treatment: a known animal-related injury risk that insurers price, restrict, or exclude based on aggregate claims data rather than any individual hive’s actual temperament. Just as a mixed-breed dog with a restricted breed in its lineage can still trigger an exclusion, a well-managed, gentle hive doesn’t automatically escape the same underwriting caution applied to bees as a category. The practical takeaway is the same in both cases: don’t assume your own animal’s good behavior exempts you from a category-wide underwriting policy, and confirm the specifics in writing rather than assuming reasonableness will carry the day.
When Beekeeping Crosses Into Business Insurance Territory
Selling honey, nucs, or other hive products — even occasionally, even just at a local farmers market — typically pushes your beekeeping activity outside what a standard homeowners policy is designed to cover. Peggy Garnes, president of the Ohio State Beekeepers Association, put it plainly in an Ohio Farm Bureau interview: “when a beekeeper is selling honey, that’s a whole other issue.” Commercial-scale operations selling to food manufacturers need food safety plans following Federal Good Manufacturing Practices and audit programs, while hobbyists selling at a market or festival still need product liability coverage in case something in their honey causes harm to a buyer. Many markets and craft fairs specifically require a certificate of liability insurance before you’re allowed to set up a table at all. For the tax side of scaling up from hobby to business, our guide to whether beekeeping is tax deductible covers the hobby-versus-business distinction the IRS applies, which runs alongside — but separately from — the insurance question.
Keeping Hives on Someone Else’s Property
It’s increasingly common for beekeepers to place hives on land they don’t own — a friend’s rural acreage, a farm offering pollination space, or a community garden plot. This arrangement introduces a liability question that doesn’t resolve itself automatically: if the hive is stolen, a worker on the property gets stung, or pesticide drift from a neighboring field wipes out the colony, whose insurance is responsible? According to Nationwide farm product manager Derek Bredlow, speaking in the same Ohio Farm Bureau piece, anyone renting or borrowing land for beehives needs “the appropriate liability contract in place that properly transfers liability and responsibility from the owner to the person who is renting.” Without that agreement in writing, both parties can end up in a dispute over which policy, if any, actually applies.
Dedicated Beekeeping and Farm Liability Insurance
For beekeepers who want real protection beyond what a homeowners policy offers, dedicated beekeeping insurance exists specifically to close this gap. This kind of coverage typically extends to liability for more serious injuries, physical damage to hives themselves, and in some programs even the value of the bees lost to specific covered events — none of which a standard homeowners policy reliably covers. It can also extend to product liability once you start selling honey or other hive products commercially. The American Beekeeping Federation maintains a dedicated beekeeper insurance program for members, and regional farm bureaus and agricultural insurers like Nationwide offer farm-liability riders that can be added to an existing policy rather than requiring an entirely separate one. Talking to an agent who has specifically handled agricultural or apiary risk, rather than a generalist, tends to produce better-fitted coverage than working through a standard homeowners renewal conversation.
A personal umbrella policy is the middle option many serious hobbyists and small commercial beekeepers choose. Standard homeowners liability limits often start around $100,000, and a single severe anaphylactic-reaction claim can realistically exceed that; an umbrella typically adds $1–2 million of liability on top of the base limit, often for well under $300 a year. Dedicated beekeeping liability programs also exist (BeeInsure is one U.S. example marketed specifically to beekeepers) for those who want coverage written around apiary risk rather than general homeowners language that was never drafted with hives in mind.
Practical Steps Before Your First Hive Arrives
Before placing your first hive, call your current homeowners insurance agent and describe your plans specifically — how many hives, hobby or eventual sales, on your property or elsewhere — rather than assuming a general mention of “having some bees” is sufficient disclosure. Confirm in writing what is and isn’t covered, ask directly about the non-renewal risk after a claim, and get a clear answer on whether an umbrella or excess liability policy would extend meaningfully better protection than your base homeowners liability limit. If you’re placing hives on land you don’t own, put a liability-transfer agreement in writing before the bees arrive, not after an incident forces the conversation. And if you’re already registered with your state’s apiary program, keep that registration paperwork on hand — insurers sometimes ask for it as part of underwriting a farm or agricultural liability add-on.
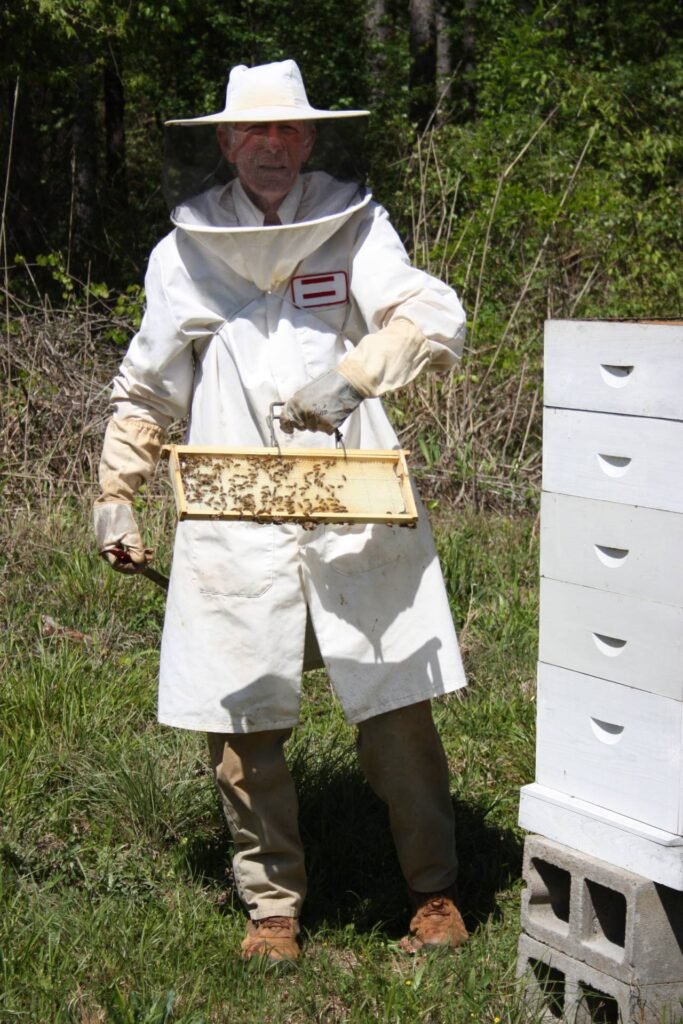
What’s Typically Covered vs. Excluded
| Item | Typically Covered | Typically Excluded / Needs More |
|---|---|---|
| Hive equipment (boxes, frames) | Yes — personal property / other structures | — |
| The bees themselves | — | Frequently excluded outright |
| Sting liability, compliant hive | Usually, if you weren’t negligent | — |
| Sting liability, known aggressive hive | — | Excluded if negligence is shown |
| Honey or product sales | — | Needs business/product liability coverage |
| Hives on rented/borrowed land | — | Needs a separate liability-transfer agreement |
When Wild Bees Damage Your House: Removal vs. Resulting Damage
The sections above deal with hives you keep on purpose. The other way bees and homeowners insurance collide is a wild colony moving into a wall, soffit, or attic. This is educational information, not insurance or legal advice — policy language, endorsements, and state rules vary by carrier, so confirm specifics with your own agent or adjuster before filing or declining to file.
Two separate costs are wrapped up in almost every “bees in my house” situation, and a standard policy treats them completely differently. The cost of removing the colony — hiring a beekeeper or pest control company to extract the bees, comb, and honey — is essentially never covered, regardless of how the bees got there or how long they have been present. The cost of repairing structural damage the colony caused — a collapsed section of ceiling drywall, warped framing, walls stained by honey seepage — is sometimes covered, but only under a narrow set of conditions, and your standard deductible (commonly $500–$2,500) still applies to whatever portion is approved.
Why Bee Damage Is Excluded by Default
The ISO HO-3 policy form, the base template most U.S. home insurers build their standard homeowners policy on, contains an explicit exclusion for damage caused by “birds, vermin, rodents, or insects,” and separately excludes nesting, infestation, or the discharge of waste products by any of these. Bees fall squarely inside that exclusion. The logic is the same one that governs termites and rodents: a policy covers sudden, accidental losses, not gradual problems a reasonably attentive homeowner could have caught, so an ongoing colony sits in the same category as wear and tear rather than a lightning strike.
The “Ensuing Loss” Exception
Most standard policies still pay for damage from a covered peril that results from an excluded cause — a principle adjusters call the “ensuing loss” exception. The classic example involves rodents: the policy will not pay to fix wiring a rat chewed through, but if the exposed wire sparks a house fire, the fire damage is covered because fire is a named peril. The bee equivalent usually involves weight and water rather than fire. A colony left undisturbed for a season or more can build enough comb and store enough honey inside a wall or ceiling cavity to add real weight; if that weight, or water intrusion from honey seeping through drywall, causes a sudden structural failure, the collapse itself may be treated as a covered event even though the colony that caused it is not. Still excluded either way: the bees, the comb, the honey removal, and any repair classified as addressing “infestation” rather than the discrete structural failure.
The Timeline Problem: Sudden vs. Long-Term
This is where most bee-damage claims are actually decided. Adjusters distinguish damage that happened suddenly from damage that accumulated through a problem the homeowner reasonably should have noticed. A colony established in an attic for two or three years, with visible staining, an audible hum, and bees observably coming and going the whole time, reads as neglect. The same physical damage from a colony that moved in recently and caused a collapse within weeks has a real chance of being treated as the sudden, covered kind of loss. Expect the adjuster to ask how long you were aware of the bees before you called anyone; that answer does real work in how the claim is classified. For more background, see Policygenius on bee removal and home insurance.
Protecting a Future Claim, Starting Today
Whether you currently have bees in a wall or not, a few habits improve your position if this ever comes up:
- Document the moment you first notice activity. A dated photo of a small entry hole or a few bees, taken the day you first saw them, is the strongest evidence that damage was addressed promptly rather than ignored.
- Call a professional quickly rather than waiting. The gap between “we noticed bees” and “we called someone” is exactly what an adjuster measures when assessing neglect.
- Keep the removal invoice and any photos the technician takes. A professional removal often documents comb size, structural condition, and damage extent; ask for this explicitly if it is not offered.
- Read your policy’s actual exclusion language once, before you need it. Not every insurer uses identical wording, and some regional or older policies differ from the standard ISO HO-3 language described here.
Frequently Asked Questions
Will my homeowners insurance cover a stolen beehive?
The equipment itself may be covered under personal property or other-structures coverage, but the bees inside are frequently excluded, so check your specific policy language.
Am I liable if my neighbor gets stung by my bees?
Generally only if you can be shown to have been negligent, such as ignoring a known aggressive hive or violating a local setback rule — a simple, compliant hive causing an isolated sting is a much harder liability case.
Can my homeowners insurance drop me after a bee-related claim?
Yes. Insurers can choose not to renew a policy after a paid claim establishes a known, ongoing risk, even if the original claim itself was small.
Do I need business insurance if I only sell honey occasionally?
Likely yes for product liability purposes — many farmers markets and craft fairs require a certificate of liability insurance before you can sell, regardless of how small the operation is.
What’s the difference between homeowners coverage and dedicated beekeeping insurance?
Dedicated beekeeping insurance typically covers more extensive injury liability, hive damage, and sometimes the bees themselves — protection standard homeowners policies don’t reliably extend to bee-related losses.
Will homeowners insurance ever pay to remove bees from my house?
Almost never. Standard policies based on the ISO HO-3 form explicitly exclude damage and infestation caused by birds, vermin, rodents, or insects, which includes bees, so removal is treated as a homeowner cost regardless of how the colony arrived.
What is the “ensuing loss” exception and does it apply to bees?
It is the principle that damage from a covered peril resulting from an excluded cause can still be paid. For bees, it can apply when honeycomb weight or honey-related water damage causes a sudden structural failure such as a ceiling collapse, even though the colony and its removal remain excluded.
Does it matter how long the bees have been in my house?
Yes, significantly. Adjusters separate sudden, accidental damage from damage that built up gradually and should have been addressed sooner. A colony established for years reads as a maintenance issue; a recent colony causing sudden failure has a better chance of qualifying under the ensuing-loss exception.
Image credits: Photo: Ich, CC BY-SA 4.0, via Wikimedia Commons.